Snowy 2.0’s price tag has blown out to up to $25 billion, another increase from the original $2 billion when it was announced in 2017. With tunnelling only 65% complete, the 2,200 MW pumped hydro project isn’t expected to deliver first power until early 2029.
Alinta Energy has abandoned its $1.8 billion, 900 MW Oven Mountain pumped hydro scheme in northern NSW, citing economic and timing challenges including a critical transmission line. It’s the second largest NSW project scrapped this month, after Origin’s Skye Ridge Wind Farm, as falling battery costs undercut pumped hydro.
WEM news: AEMO has set the 2028-29 Reserve Capacity Prices at $459,192/MW/year for Peak capacity and $244,250/MW/year for Flexible capacity, alongside the assignment of capacity credits for the 2026 Reserve Capacity Cycle.
NextDC expects its future earnings to fall by about a third after West Footscray residents stalled Jemena’s rollout of 15-metre, 66 kV power poles to its Melbourne M3 data centre by parking their cars in the street to block the work trucks. Morningstar expects community pushback like this to drive new data centres further from built-up areas.
A new alliance of Queensland community groups, backed by Nationals leader David Littleproud, is calling for tougher rules on wind and solar developments, including minimum 3 km setbacks from homes and up-front decommissioning bonds. It follows growing frustration among neighbours of projects, such as Stanwell’s Wambo Wind Farm, and adds to planning risk for the Queensland renewables pipeline.
NSW spot prices hit $23,107/MWh on 12 October when a spring heatwave coincided with coal outages. Amber Electric’s roughly 30,000 customers earned about $2 million in two hours by exporting from home batteries during the spike, which raises questions about AEMO’s lack of visibility over behind-the-meter storage.
Paywalled: LNG importers across Asia are pushing back on the federal government’s plan to make exporters reserve gas for the domestic market, putting Australia at odds with the region’s major energy buyers. The outcome will shape east coast gas supply and prices for gas-fired generation.
News from Japan
Paywalled: METI is considering raising the fee for grid connection applications, which hasn’t changed since 2012 (¥220,000, about AUD 2,000), to stop BESS developers from holding grid capacity without firm plans. Applications have jumped from 1,599 in FY2023 to nearly 25,000 in FY2025, and earlier measures like a higher deposit and caps on applications per developer haven’t slowed them.
Podcast of the week
BloombergNEF’s Switched On looks at why gas turbine makers are cashing in on the global power rush. With orders surging, delivery slots scarce and data centres driving demand, they ask how long the boom can last and whether manufacturers can expand without repeating past overcapacity.
NSW is letting gas into its renewables scheme, with ASL consulting on a firming LTESA tender designed specifically to support gas-fired plants, a sharp contrast to the federal Capacity Investment Scheme, which excludes gas.
ASL’s 2026 Firming IIO Report sets a 1,500 MW pathway for new NSW firming capacity by May 2033 to cover the retirement of Bayswater and Vales Point, with projects needing to deliver for at least eight hours and a first tender due in 2027.
Victoria has given final state approval to WestWind Energy’s 1.5 GW Warracknabeal Energy Park, a 219-turbine wind farm with two 300 MW batteries that would be the largest in the Southern Hemisphere, though critics warn it depends on transmission lines like VNI West and the Western Renewable Link that are far from built.
The Climate Council warns coal and gas miners are using a Safeguard Mechanism loophole, classing projects as expansions rather than new facilities to avoid stricter best-practice limits, which it estimates will add 4.5 Mt of CO2 a year by 2035.
A new ACCR report argues WA doesn’t need Woodside’s Browse project to avoid a domestic gas shortfall from 2030, since exporters could supply more from existing projects, a claim rejected by Woodside, industry veterans and the Cook Government.
SA Energy Minister Tom Koutsantonis has hinted for the first time that SA may miss its 100% net renewables target for 2027, possibly slipping into 2028, after delays to the SA–NSW interconnector stalled new wind investment, though the state’s pipeline is now rebounding to nearly $32.5 billion of projects under construction or approved.
Endgame Analytics’ latest whitepaper puts Byron Bay under the microscope. Using connected vehicle data from Compass IoT, we modelled what an extra 6,000 visiting EVs would mean for peak demand on the local substation.
The case study looks at a peak visitor day, when around 40,000 visitors join the town’s 11,500 residents, and assumes half of all visiting vehicles are electric.
Zugzwang: Episode 5 – Networks, power poles and the EV charging gap
The latest episode of Zugzwang: The market modelling podcast is now available!
Jack Simpson and Oliver Nunn are joined by Endgame Director Martin Chow and Russell Pendlebury, General Manager of Regulation and Policy at Energy Networks Australia, to dig into proposed rule changes that would let networks install curbside EV chargers on ordinary suburban power poles, and what it means for equity, network costs and bills.
The High Court has dismissed MACH Energy’s appeal, keeping its Mount Pleasant coal mine expansion on hold after ruling the NSW planning commission should have considered the emissions from burning the mine’s exported coal overseas.
Wagga Wagga residents have launched a petition against CDC’s proposed $15 billion, 1.4 GW data centre, which is expected to use as much electricity each year as 1 to 1.5 million NSW homes.
Tesla and major energy retailers are fighting a proposed “EV charger tax” that would let grid operators install EV chargers on their power poles and recover the cost from all electricity customers, including people who don’t drive EVs.
Nvidia-backed AI data centre builder Firmus has pulled its $44 billion ASX float, which would have been the biggest since Telstra, after investors balked at its valuation and debt levels.
To tax or not to tax EVs (ABC Business Daily): Carrington Clarke and the e61 Institute’s Amy Tramontozzi explain what surging EV uptake and falling fuel excise revenue mean for the budget and how vehicles on our roads should be taxed.
The government’s Australian Energy Update 2026 shows Australia’s total energy use fell 5% as electric vehicles, rooftop solar and growing renewable generation replace fossil fuels.
Sydney solar retailer Macarthur Energy has collapsed owing $3.4 million to creditors, leaving customers out of pocket by up to $17,600 for batteries never installed and raising questions about consumer protections under the federal Cheaper Home Batteries Program.
Marinus Link has begun its next construction phase with a sod-turning ceremony for the undersea interconnector between North West Tasmania and Victoria’s Latrobe Valley, with the related transmission works due in service by 2030.
News from Japan
Paywalled: Kyushu Electric’s incoming president, Norihiro Nakamura, says the utility is considering building new nuclear capacity, as demand in the region grows from AI data centres and semiconductor hubs such as TSMC’s.
Paywalled: TEPCO is tightening its grid connection rules to stop data centre developers holding queue spots without firm plans; from October 2026, it will cancel requests if the initial construction deposit (10% of estimated costs) isn’t paid within three months, or if development plans change during the application stage.
Victoria will ban datacentres from residential zones and within 150 m of homes, schools and childcare centres, and require them to supply their own renewable energy and storage; critics point out that the rules aren’t retrospective, exempting all approved projects and the eight applications already before the planning minister.
With AEMO forecasting that datacentre electricity use could triple by 2030, the AEMC has opened consultation on two rule changes from Minister Bowen that would make datacentres and other large loads pay their share of the network upgrades they trigger, and stop the cost of stranded assets being passed to other consumers if projects fall through. Submissions close 5 November.
Treasury’s Intergenerational Report 2026 names the energy transition as one of five forces reshaping the economy over the next 40 years, projecting that household energy costs will fall around 40% between 2030 and 2050 as homes electrify, and that data centres will make up almost 10% of NEM demand by 2050.
Woodside and Burrup Peninsula Traditional Owners are locked in a $300 million compensation dispute over the 1998 land access agreement for the North West Shelf’s Karratha Gas Plant – the Ngarluma Yindjibarndi Foundation is seeking $390 million over 12 years against Woodside’s offer of $87 million.
Chris Bowen is travelling to India and Saudi Arabia to bolster fuel security, with plans to visit the world’s largest refinery at Jamnagar and meet Saudi Energy Minister Prince Abdulaziz bin Salman about the closure of the East-West pipeline, ahead of COP31.
Sunshine and wind met a record 80.4% of demand on the NEM on Saturday 19th September, with rooftop solar alone supplying more than half the grid’s power for 30 minutes around lunchtime.
Columbia Energy Exchange looks at the Iran war six months on. With crude near $107 a barrel, Hormuz tanker traffic reduced and Saudi Arabia’s East-West Pipeline offline, they warn that the market buffers that cushioned the early shock are running out.
Anthropic has signed a lease for Australia’s largest data centre, the $32 billion Western Downs Digital Park near Dalby in Queensland, which will power Claude AI inference and, once built, draw electricity equivalent to 1.5 million households.
Australia’s dependence on gas generation during the evening peak has fallen by almost 70% in the year to August 2026, with batteries now covering 49% of evening dispatchable power, up from just 0.4% in 2020.
NSW’s renewable transmission delivery agency EnergyCo has underspent its budget by $939 million over the past two years, a symptom of approval delays that now leave the state roughly 7.9GW short of its 2030 renewable energy target.
ARENA has committed $8.2 million to a home electrification trial that aims to make the transition from gas to electricity easier, letting up to 1,000 Canberra households bundle solar, batteries and EVs onto one digital platform.
IEEFA and Green Energy Markets’ Australian Renewable Energy Scorecard finds Australia has enough wind and solar in the pipeline – 34GW of solar and 17GW of wind fully approved – to hit the 82% 2030 renewables target, but actual construction is falling far short.
News from Japan
Chubu Electric Power has withdrawn its restart applications for Hamaoka Units 3 and 4 after an independent committee found staff had for years manipulated seismic safety data submitted to Japan’s nuclear regulator, leaving it unclear if or when the reactors will ever restart.
Podcast of the week
Zugzwang: Episode 3 – What is transmission really worth?
The latest episode of Zugzwang: The market modelling podcast is now available!
Jack Simpson, Oliver Nunn and Jabez Wilson discuss modelling philosophy and put it to work on one of the NEM’s most contested assets: transmission. Listen now on your favourite platform.
The Albanese Government has softened its east coast gas reservation policy, replacing a fixed 20% mandatory reservation on LNG exporters with a cap of up to 20% determined by the Australian Energy Regulator.
Something closer to home: Sydney’s International Convention Centre is being fitted with roughly 4,500 new rooftop solar panels, creating the largest solar farm in any city centre in the Southern Hemisphere and cutting the venue’s carbon emissions by up to 2,000 tonnes a year.
Transgrid’s newly released 2026 Transmission Annual Planning Report shows NSW data centre demand forecasts have quadrupled since last year’s report, with data centres now expected to reach around 3.5GW of peak demand by 2035 and drive 66% of all growth in the state’s end-use electricity consumption over the next decade.
Transgrid has also effectively put up a “house full” sign for new data centres in Sydney, revealing it has received 20GW of connection requests over two years but signed just 1.5GW, and is now steering data centre owners toward regional NSW until major transmission upgrades complete around 2035.
News from Japan
Australia’s ambassador to Japan, Andrew Shearer, used a Japan National Press Club address to call for deeper Australia-Japan energy cooperation, framing the push partly around concerns over China’s growing economic coercion in the region.
Paywalled: Chugoku Electric Power’s Shimane Nuclear Power Station Unit 3 – a 1.37GW reactor that began construction in 2006 but was halted after Fukushima in 2011 – is on track to clear safety inspections and become the first new nuclear unit to come online in Japan, with operation expected by FY2030.
Paywalled: Kawasaki Heavy Industries and Germany’s RWE are installing a 30 MW-class hydrogen mono-firing gas turbine in northern Germany, capable of running on 100% hydrogen or co-firing with LNG at various ratios, with the trial run set to begin within FY2026.
Podcast of the week
Catalyst with Shayle Kann asks whether data centers actually increase electricity prices; the answer is more nuanced than it first appears, with data centres able to lower local utility rates even as they contribute to rising grid costs elsewhere.
A fire has completely destroyed Tungatinah Power Station in Tasmania’s Central Highlands; Hydro Tasmania and TasNetworks remain confident the wider grid remains secure with the gas-fired Tamar Valley Power Station coming online to cover the shortfall.
WA’s Economic Regulation Authority has fined state-owned Synergy $1.2 million after a trading software error let it inflate wholesale prices from its Kwinana battery, extracting an extra $850,000 and lifting overall wholesale costs by roughly $9.5 million over an eight-month period.
AEMO and SA Power Networks ran their annual rooftop-solar “fire drill for the grid,” remotely curtailing tens of thousands of South Australian solar systems for up to an hour to test the emergency backstop system.
The AER has released a preliminary position rejecting Transgrid’s bid to pass an extra $1.2 billion of Project EnergyConnect cost blowouts onto consumers.
Victoria has launched Australia’s first offshore wind auction, seeking 2GW of capacity in the Gippsland zone with bids closing in August 2027, as the state races to replace coal capacity ahead of Yallourn’s 2028 and Eraring’s 2029 closures.
News from Japan
Japan’s industry ministry has asked Hitachiomiya City, near Tokyo, to accept a two-year literature survey on hosting the country’s final high-level nuclear waste repository, only the second time the central government has proactively requested a site rather than waiting for a local volunteer.
Podcast of the week
The latest episode of Zugzwang: The market modelling podcast is now available! In this episode Jack Simpson, Oliver Nunn and Endgame consultant, Harry McArthur break down our latest modelling on where data centres should be located – and what it means for prices, gas, and the coal fleet along the way. Listen now on your favourite platform.
AEMO’s 2026 Electricity Statement of Opportunities shows an improved reliability outlook with gaps not emerging until 2030-31 in NSW and Victoria under the official standard; WattClarity questions whether that improvement is partly an artefact of a contested 2023 methodology change adding 6-12 month buffers before new projects count toward the forecast.
Chris Bowen has launched Capacity Investment Scheme Tender 11, seeking 1.8GW of wind and solar in WA to help replace coal plants closing by 2029. In spite of this, recent analysis from the ABC shows that only 4 of 31 Capacity Investment Scheme-backed wind projects reaching financial close as construction costs have risen 30-50% since bids were submitted.
The AER has released its Strategic Plan 2026-2030 with concrete commitments including implementing an effective domestic gas reservation scheme and driving more efficient utilisation of electricity distribution networks.
Victoria has opened its first offshore wind auction, seeking 2GW of capacity across Gippsland and Warrnambool zones (enough for 1.5 million homes), with bids closing August 2027, contracts awarded in 2028, and first power expected in 2035.
The Australian Renewable Energy Hub has shrunk from a planned 26GW to 15GW, with proponents InterContinental Energy and CWP Global dropping the hydrogen and ammonia export components entirely.
Oxford Economics forecasts Australian data centre electricity demand will more than triple from 5.1TWh in FY26 to 33.7TWh by FY36 under its central scenario, with NSW and Victoria accounting for over 85% of that load and data centres consuming up to 19% of those states’ grid-supplied electricity by then.
News from Japan
Paywalled: Kirin has begun producing green hydrogen on-site at one of its beer factories using a 280kW solar array, targeting 70-80 tonnes of hydrogen annually to cover up to 23% of the plant’s heating needs.
Paywalled: Japan’s grid operator OCCTO has proposed a new “Complementary Auction” within its Capacity Market, run alongside the existing Reserve Power auction, both effectively paying older thermal plants to stay online amid concerns that supply will remain tight through FY2030.
Podcast of the week
Catalyst with Shayle Kann talks to Voya Energy’s Richard Wang about replacing diesel backup generators with an electrochemical generator that produces electricity from aluminium pellets and air.
What cancelling VNI-West means for the energy market and the future power system
VNI-West sits in the forward plan for the NEM, but its future is now uncertain. It has been the subject of a long and difficult public debate about cost, route and land use, and there is a live possibility that the project does not proceed. Most of the analysis published on the project to date has been directed at the explicit cost of the project. Comparatively little has been directed at what the world looks like with and without the project, and in particular the key question: what does the power system look like without VNI-West and what must happen in its place?
Against this backdrop, in this article we consider a range of projections to improve our understanding about the consequences of the project not proceeding. We do not seek to express views on the non-quantitative merits of the project, on whether its costs are reasonable, on the land use and social licence questions along the route. Those are matters to which a model has nothing useful to contribute. What a model can do is trace the consequences for the power system, the electricity market, and the broader energy system.
We take our reference case for the NEM, remove VNI-West, and consider what happens when we do nothing, or when we allow the model to re-optimise the generation and storage build in response. We consider three questions:
What happens to prices, in Victoria and elsewhere?
What does the system build instead?
What does that build do to gas consumption?
The short answer is that the price effect is large and it persists, the system does not really replace the interconnector so much as run a more expensive version of itself without it, and the difference is accounted for by increased consumption of gas for power generation.
Where the project stands
VNI-West entered the 2022 ISP as a staged actionable project. AEMO Victoria Planning and Transgrid published the PACR in May 2023, identifying a 500 kV double-circuit line from Bulgana on the Western Renewables Link to Dinawan on Project EnergyConnect as the preferred option. AEMO ran the feedback loop against the 2023 IASR and the Draft 2024 ISP in December 2023 and confirmed the project remained on the optimal development path, and the AER approved the Stage 1 early works contingent project application in May 2024.
The project has been retained as actionable in the 2024 and 2026 ISPs. Over that period the Victorian route has moved, the delivery vehicle has changed, and the cost estimate has risen from a little under $4.0 billion at the time of the Stage 1 application to $7.6 billion in the 2026 ISP, carried with an accuracy range of minus 30 to plus 50 per cent.
Our method
We start from our headwinds reference case for the NEM and construct three cases for comparison.
The first is the base case, with VNI-West delivered on its current timing in our reference case. Importantly, our reference case already assumes delays to VNI-West.
The second is the naive removal case. We take VNI-West out of the forward plan and change nothing else – the same generation and storage build, in the same places, at the same times. This is deliberately artificial.
The third is the re-optimised case. We take VNI-West out and let the model rebuild: generation, storage and firming are all free to respond, subject to the same build limits and connection constraints as the base case.
We report outcomes on our standard weather reference year, but also for some charts on a 2011 weather reference year. The 2011 reference year combines a harsh summer with a winter that sees sustained wind droughts across the southern states. Chart 2 explains why the choice of reference year does a great deal of the work in this analysis.
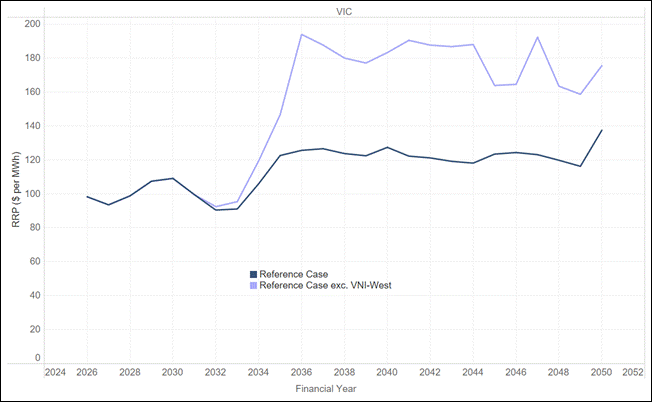
Chart 1 – The naïve price effect in Victoria, and how long it lasts
Chart 1 shows average annual spot prices in Victoria for the reference case and the naïve case without VNI-West. The two cases are indistinguishable to FY2033. They separate in FY2034, and by FY2036 the case without VNI-West is at $194 per MWh against $126 in the reference case. From that point the gap averages around $56 per MWh and never closes. It is at its widest in FY2036 and again in FY2044, at close to $70 per MWh, and at its narrowest in the mid-2040s, at around $40. In the last year of the outlook it is still $38.
Chart 1 – Removing VNI-West lifts Victorian prices by around $56 per MWh from FY2036
Average annual spot price in Victoria, reference case versus reference case excluding VNI-West
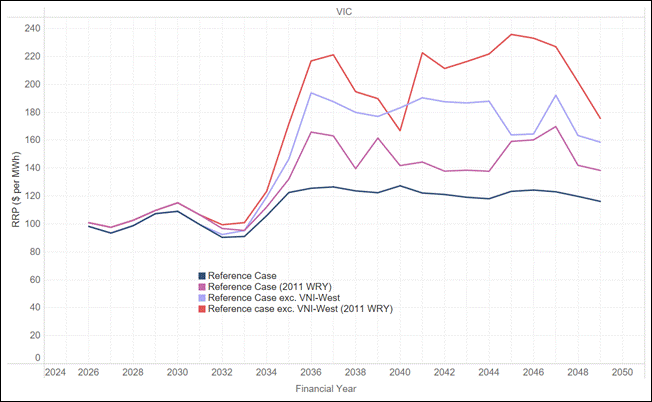
Chart 2 – Outcomes under a 2011 weather reference year
Chart 2 adds a 2011 weather reference year to both cases, giving four lines: the reference case and the case without VNI-West, each run on standard weather and on the 2011 trace. The price level rises sharply. Without VNI-West, a 2011 trace produces Victorian prices above $210 per MWh in six years of the outlook and a peak of $236 per MWh in FY2045, against $124 in the reference case on standard weather in the same year.
Chart 2 – Under a 2011 reference year the removal effect is markedly greater
Average annual spot price in Victoria, standard weather and 2011 weather reference year
An interconnector earns its keep on a small number of days a decade, under exactly the conditions the 2011 trace reproduces, because that is when the diversity between regions is doing the heaviest lifting. Averaging across reference years does to an interconnector what averaging across a year does to a peaker: it produces a number that is arithmetically correct and analytically useless.
We made a version of this point in our November 2021 Chart of the Month on Vic-NSW. Interconnectors derive a large part of their value from the uncertainty of future outcomes, because they increase the diversity of supply options, and yet the models used to value them are typically deterministic and assume perfect foresight. If we know the future, there is no value in a hedge against uncertainty. Five years on, the models have improved at the margin, but the point still stands.
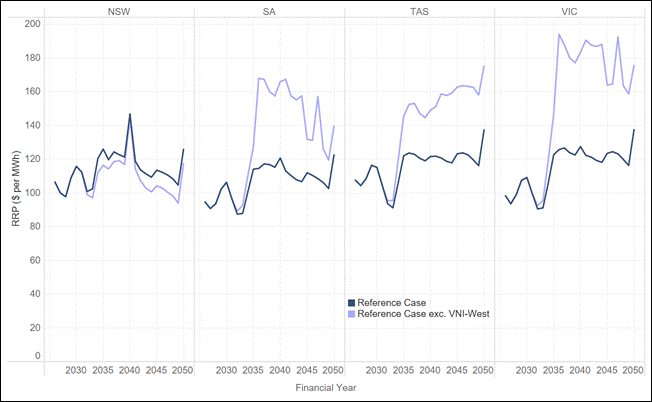
Chart 3 – This is not just a Victorian question
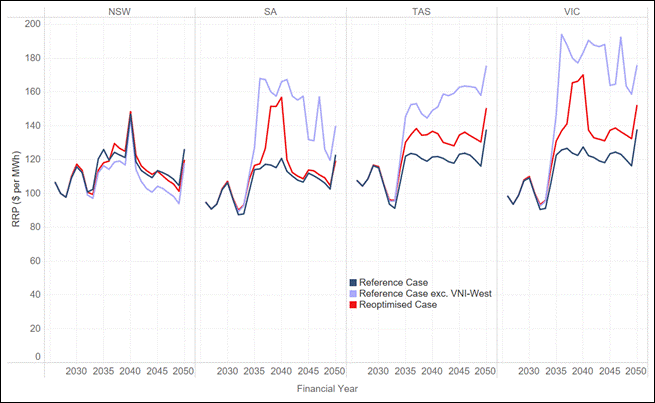
Chart 3 shows the same comparison across four regions. South Australia is affected almost as heavily as Victoria. Prices without VNI-West run around $50 per MWh above the reference case from FY2036 through to the mid-2040s, peaking near $168 per MWh in FY2036 against $114. Tasmania is $30 to $45 per MWh higher over the same period. New South Wales moves the other way: from the early 2040s, prices there sit some $5 to $12 per MWh below the reference case, because energy that would have moved south stays in the region.
Chart 3 – South Australia and Tasmania bear price increases nearly as large as Victoria
Average annual spot price by region, reference case versus reference case excluding VNI-West
The mechanism is not complicated, but it is routinely missed. Interconnectors also affect prices in neighbouring regions, sometimes for the better and sometimes for the worse. The practical consequence is that the effects of the decision are not restricted to Victoria, and they are not symmetric. A change of $50 per MWh in South Australia is not a rounding error.
Chart 4 – What the system builds instead
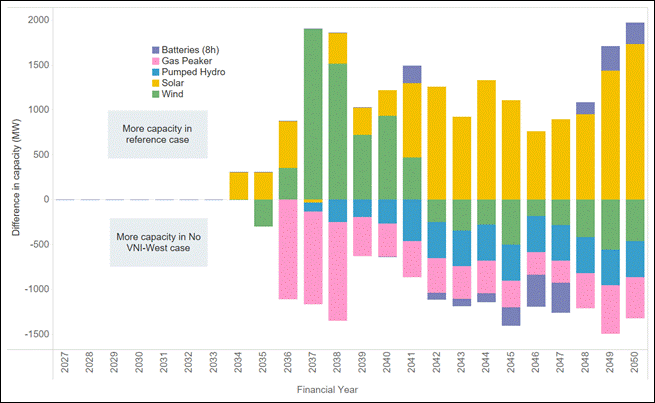
We now turn to the re-optimised case. Chart 4 shows the difference in new capacity between the base case and the re-optimised case by technology and year. Bars above the line are capacity the reference case builds but the removal case does not; bars below the line are capacity built only in the case without VNI-West.
The first thing to say is that this is not a replacement. Without the network, the renewables cannot be delivered, so the model does not build them. It builds a smaller, more gas dependent fleet and runs it harder.
Chart 4 – The system does not replace VNI-West. It substitutes gas peaking and deep storage for VRE
Difference in new capacity by technology and financial year, reference case less case excluding VNI-West
Underneath the total there is a clear substitution. Through FY2036 to FY2038 the reference case builds around 1.5 GW a year more solar and wind, while the removal case brings forward roughly 1.2 to 1.5 GW a year of gas peaking. The pattern continues with more gas and deep storage replacing more wind and solar. Interestingly the No VNI-West case builds materially more pumped hydro as it tries to firm a system that no longer has a second path to New South Wales.
The replacement is not like-for-like in either technology or location: it is gas peaking and deep storage in place of solar, wind and network, sited to reach load on the existing system rather than to reach the resource.
Chart 5 – The consequences for prices under the re-optimised case
So what does this mean for prices. Chart 5 shows the same analysis as Chart 3 but now includes prices for the re-optimised case. The important point here is that the price increases associated with the new build case persist. The reason for this is the increased use of gas for power generation in the Southern states.
Chart 5 – Even with re-optimisation the price increases persist in Victoria and Tasmania
Average annual spot prices, reference case versus re-optimised and reference case excluding VNI-West
Chart 6 – The consequence for gas under the re-optimised case
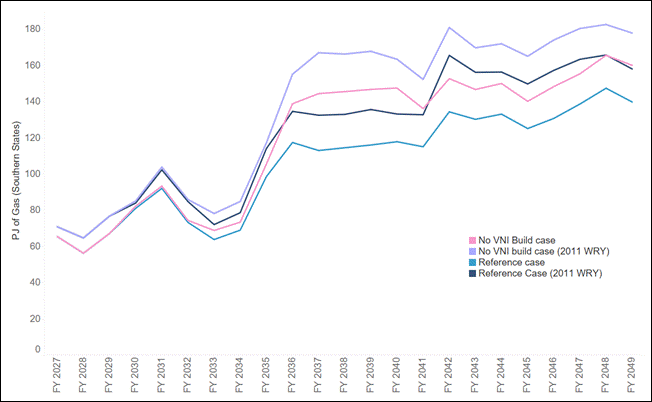
Chart 6 shows gas consumption for electricity generation in the Southern States across all four cases: reference and re-optimised, each on standard weather and on the 2011 trace. Gas burn rises by roughly 20 to 28 PJ a year from the mid-2030s onwards, an increase of between a third and a half on the reference case. The divergence opens in FY2035 and, like the price effect, does not close. The extreme weather year is when the system most needs gas, and removing the interconnector also raises the requirement.
Chart 6 – Southern states’ gas consumption rises by 25 PJ a year, more under a 2011 reference year
Gas consumption for GPG in Southern States, 2015 and 2011 weather reference years
The southern gas market is already tight. Southern supply has been declining faster than southern demand for some years, the balance is met by northern gas moved south through pipeline capacity that is fully subscribed on peak days, and it is peak-day capability rather than annual quantity that binds.
We cannot be certain whether that gas can be delivered, because much can happen in the domestic market between now and the 2030s. But we can say that it is one of the questions on which the removal case turns.
Our two cents
The system does not replace VNI-West, it substitutes for it, and the substitution is worse. We expected the model to build its way back to something close to the reference case outcome and it does not. It leans on gas peaking and deep storage, and leaves Victorian prices around $20 per MWh higher for the rest of the outlook. Removing an asset like this from the forward plan is not a decision to avoid a capital cost. It is a decision to accept a permanently more expensive system unless something cheaper is put in its place.
The price effect does not fade, which is unusual and which changes how the decision should be framed. In most of the work we do, a shock to the system produces a transitional price effect that closes once the build catches up. Here the build has fifteen years to catch up and does not. We are removing a key piece of strategic infrastructure from the grid. A decision framed as a saving of $7.6 billion in capital is, on these results, a decision to add tens of dollars per megawatt hour to southern prices indefinitely.
The value of a line like VNI-West is the value of an option, but we keep measuring it as though it were a pipe. Chart 2 is revealing – the value under the 2011 weather year is markedly higher than under a median year. The value is concentrated in the tail events, and a framework that prices interconnectors on median outcomes across a scenario weighting will underprice it in a way that is superficially rigorous. This is a general problem with how we (as an industry) value network assets – not a feature of VNI-West.
The effects are national and they are not symmetric. South Australia carries an increase of up to $30 per MWh and Tasmania up to $20 per MWh, while New South Wales is slightly better off. This shows that this is not just an issue for Victoria, but rather a consideration for all the Southern states.
The benefit of planning certainty is itself an input to cost, and it does not appear anywhere in a RIT-T. A developer looking at any future transmission project has to price the probability that the project is unwound before it is delivered, and that probability is now visibly non-zero. A forward plan that is revisited whenever costs move or circumstances change raises the risk premium on every project that it comprises, and that premium is paid by consumers.
Applied consistently across all future transmission projects, the RIT-T and ISP framework that has been applied to VNI-West would ultimately dispose of most of the forward transmission plan. Every major line has the same profile: costs that escalate between the PACR and the final estimate, and benefits concentrated in tail years that the central case dilutes. If that combination is sufficient to remove a project from the plan, the same logic reaches into every other major transmission project. A counterfactual worth modelling is one in which the sector builds very little new transmission at all, and each region solves its problem locally with gas. That is a coherent system with an estimable cost, and we should estimate it rather than arrive at it by accident, one project at a time.
About Endgame
Endgame Analytics is an economic and mathematical consultancy that specialises in energy. We bring expertise in optimisation, quantitative analysis, and critical thinking to solve complex problems.