Skip to Content

One must imagine CIS-yphus happy

Highlights from the Australian market

News from Japan

Podcast of the week

Zugzwang: Episode 6 – Anatomy of a Trading Department

The latest episode of Zugzwang: The market modelling podcast is now available!

Jack Simpson, Oliver Nunn and Endgame Director David Scott go inside a trading team to see how the physical, contract and risk desks work. They explain why a price spike looks very different to each desk, from the contracts locked in years out to the dispatch decisions made on the day.

Spotify: https://open.spotify.com/show/0346ILtbXgKJJIlOy64p1i
Apple Podcasts: https://podcasts.apple.com/us/podcast/zugzwang/id6801348317
YouTube: https://www.youtube.com/playlist?list=PLQ3gvq2Ccils
Electrifying the Heavy Vehicle Fleet

Electrifying Australia’s truck fleet is a grid story as much as a freight one, and it will play out at the depot gate.

Endgame Analytics is pleased to share the fourth instalment of our decarbonising transport research series, this time looking at the grid implications of battery electric truck uptake: how much electricity a fully electric fleet would draw, where it would charge, and what that means for the networks that serve it.

We sized the national fleet’s energy from ABS and NTC data, then modelled least-cost charging for a 30-truck depot at Eastern Creek in Western Sydney against Endeavour Energy’s substation demand and tariffs, and scaled it to ten depots.


Some key highlights:

  • The energy task is large:A fully electric version of today’s truck fleet would draw 31.8 TWh a year, adding 14% to NEM and WEM electricity use, rising to 49.3 TWh by 2050. Articulated trucks are 22% of the fleet but would draw 62% of the energy.
  • Most charging happens at depots, at least cost: 83% of truck-km would be charged at depots. A least-cost depot charges in the early hours for about $1,015 a day, compared with about $2,860 for the same driving on diesel at $2 a litre.
  • Price signals move the peak, they don’t remove it: Ten least-cost depots would lift the Eastern Creek zone substation to about 28 MW overnight, against a 19.2 MW evening peak in 2023, leaving only about 7 MW of headroom by 2030.
  • Small operators face the biggest barrier: 70% of operators own a single truck and margins average about 2%, so connection upgrades and chargers could stall the transition without government support.


Networks will need to plan for a potential peak caused by coordinated depot charging, and add capacity.

Read the full paper here

Fill out the form to download the PDF

Yoo-hoo! Big Snowy blowout!

Highlights from the Australian market

  • Snowy 2.0’s price tag has blown out to up to $25 billion, another increase from the original $2 billion when it was announced in 2017. With tunnelling only 65% complete, the 2,200 MW pumped hydro project isn’t expected to deliver first power until early 2029.
  • Alinta Energy has abandoned its $1.8 billion, 900 MW Oven Mountain pumped hydro scheme in northern NSW, citing economic and timing challenges including a critical transmission line. It’s the second largest NSW project scrapped this month, after Origin’s Skye Ridge Wind Farm, as falling battery costs undercut pumped hydro.
  • WEM news: AEMO has set the 2028-29 Reserve Capacity Prices at $459,192/MW/year for Peak capacity and $244,250/MW/year for Flexible capacity, alongside the assignment of capacity credits for the 2026 Reserve Capacity Cycle.
  • NextDC expects its future earnings to fall by about a third after West Footscray residents stalled Jemena’s rollout of 15-metre, 66 kV power poles to its Melbourne M3 data centre by parking their cars in the street to block the work trucks. Morningstar expects community pushback like this to drive new data centres further from built-up areas.
  • A new alliance of Queensland community groups, backed by Nationals leader David Littleproud, is calling for tougher rules on wind and solar developments, including minimum 3 km setbacks from homes and up-front decommissioning bonds. It follows growing frustration among neighbours of projects, such as Stanwell’s Wambo Wind Farm, and adds to planning risk for the Queensland renewables pipeline.
  • NSW spot prices hit $23,107/MWh on 12 October when a spring heatwave coincided with coal outages. Amber Electric’s roughly 30,000 customers earned about $2 million in two hours by exporting from home batteries during the spike, which raises questions about AEMO’s lack of visibility over behind-the-meter storage.
  • Paywalled: LNG importers across Asia are pushing back on the federal government’s plan to make exporters reserve gas for the domestic market, putting Australia at odds with the region’s major energy buyers. The outcome will shape east coast gas supply and prices for gas-fired generation.

News from Japan

  • Paywalled: METI is considering raising the fee for grid connection applications, which hasn’t changed since 2012 (¥220,000, about AUD 2,000), to stop BESS developers from holding grid capacity without firm plans. Applications have jumped from 1,599 in FY2023 to nearly 25,000 in FY2025, and earlier measures like a higher deposit and caps on applications per developer haven’t slowed them.

Podcast of the week

BloombergNEF’s Switched On looks at why gas turbine makers are cashing in on the global power rush. With orders surging, delivery slots scarce and data centres driving demand, they ask how long the boom can last and whether manufacturers can expand without repeating past overcapacity.

NSW passes gas, VIC breaks wind

Highlights from the Australian market

  • NSW is letting gas into its renewables scheme, with ASL consulting on a firming LTESA tender designed specifically to support gas-fired plants, a sharp contrast to the federal Capacity Investment Scheme, which excludes gas.
  • ASL’s 2026 Firming IIO Report sets a 1,500 MW pathway for new NSW firming capacity by May 2033 to cover the retirement of Bayswater and Vales Point, with projects needing to deliver for at least eight hours and a first tender due in 2027.
  • Victoria has given final state approval to WestWind Energy’s 1.5 GW Warracknabeal Energy Park, a 219-turbine wind farm with two 300 MW batteries that would be the largest in the Southern Hemisphere, though critics warn it depends on transmission lines like VNI West and the Western Renewable Link that are far from built.
  • The Climate Council warns coal and gas miners are using a Safeguard Mechanism loophole, classing projects as expansions rather than new facilities to avoid stricter best-practice limits, which it estimates will add 4.5 Mt of CO2 a year by 2035.
  • A new ACCR report argues WA doesn’t need Woodside’s Browse project to avoid a domestic gas shortfall from 2030, since exporters could supply more from existing projects, a claim rejected by Woodside, industry veterans and the Cook Government.
  • SA Energy Minister Tom Koutsantonis has hinted for the first time that SA may miss its 100% net renewables target for 2027, possibly slipping into 2028, after delays to the SA–NSW interconnector stalled new wind investment, though the state’s pipeline is now rebounding to nearly $32.5 billion of projects under construction or approved.
  • Buru Energy has referred its Rafael conventional gas project in the Kimberley to the WA EPA, claiming it could meet all of the region’s gas demand with first gas by early 2029, though environmentalists warn it could be a “Trojan horse for fracking”.

News from Japan

New whitepaper

Endgame Analytics’ latest whitepaper puts Byron Bay under the microscope. Using connected vehicle data from Compass IoT, we modelled what an extra 6,000 visiting EVs would mean for peak demand on the local substation.

The case study looks at a peak visitor day, when around 40,000 visitors join the town’s 11,500 residents, and assumes half of all visiting vehicles are electric.

Download the whitepaper: Electrifying the Light Vehicle Fleet – Endgame Analytics

Podcast of the week

Zugzwang: Episode 5 – Networks, power poles and the EV charging gap

The latest episode of Zugzwang: The market modelling podcast is now available!

Jack Simpson and Oliver Nunn are joined by Endgame Director Martin Chow and Russell Pendlebury, General Manager of Regulation and Policy at Energy Networks Australia, to dig into proposed rule changes that would let networks install curbside EV chargers on ordinary suburban power poles, and what it means for equity, network costs and bills.

Spotify: https://open.spotify.com/show/0346ILtbXgKJJIlOy64p1i
Apple Podcasts: https://podcasts.apple.com/us/podcast/zugzwang/id6801348317
YouTube: https://www.youtube.com/playlist?list=PLQ3gvq2Ccils
Sun(ken) Cable

Highlights from the Australian market

News from Japan

Podcast of the week

To tax or not to tax EVs (ABC Business Daily): Carrington Clarke and the e61 Institute’s Amy Tramontozzi explain what surging EV uptake and falling fuel excise revenue mean for the budget and how vehicles on our roads should be taxed.

Cold snap, gas cap

What GPG constraints would mean for WEM prices

25 August 2025: the day the SWIS hit the cap

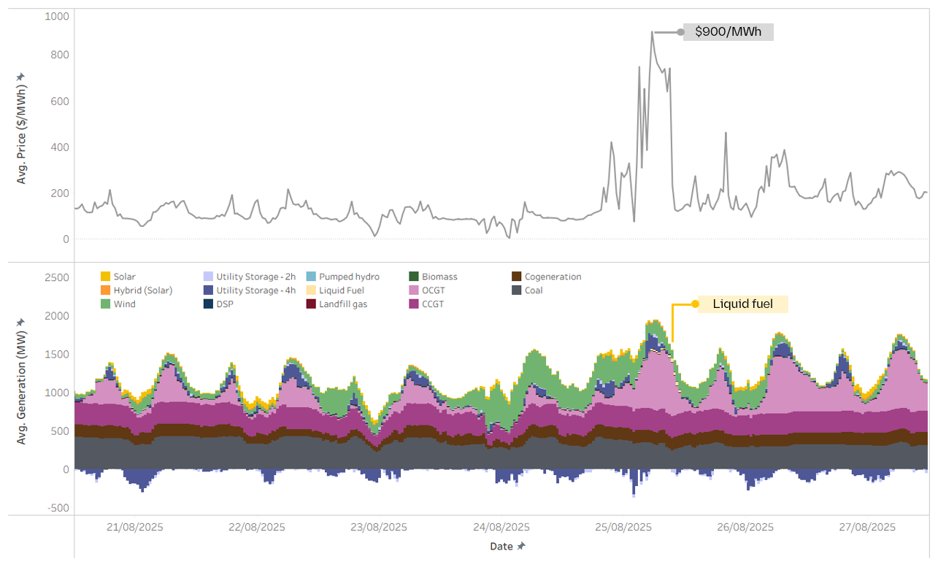
On 25 August 2025, Real-Time Market (RTM) prices reached the then market price cap of $900/MWh. A polar cold front held Perth to a maximum of 11.4°C, its coldest day in more than 50 years, and heating demand surged. At the same time, heavy cloud cover with sporadic breaks made rooftop solar generation volatile, leaving operational demand forecasts inconsistent and unstable.

The system turned to its usual answer: gas. But pipeline constraints curtailed OCGT output just when it was needed most, and liquid fuel units were brought on to cover the gap (Figure 1). Elevated daytime prices also discouraged Battery Energy Storage Systems (BESS) from charging, and their state of charge was less than 40% at the start of the ESROD period[1].

Figure 1: Average RTM price ($/MWh) and generation (MW) by technology, 21 to 27 August 2025

Source: Endgame analysis of AEMO WEM market data.

The event showed that the SWIS must withstand weather and fuel supply limits arriving together. Based on the supply conditions during the event, we estimate that gas for power generation was effectively limited to 406 TJ/day.

Repeated days like that, in a system with no coal left may bring system stress. So we asked the question: what happens to the transition if gas is constrained this way in the future?

Our reference case: SWIS Success

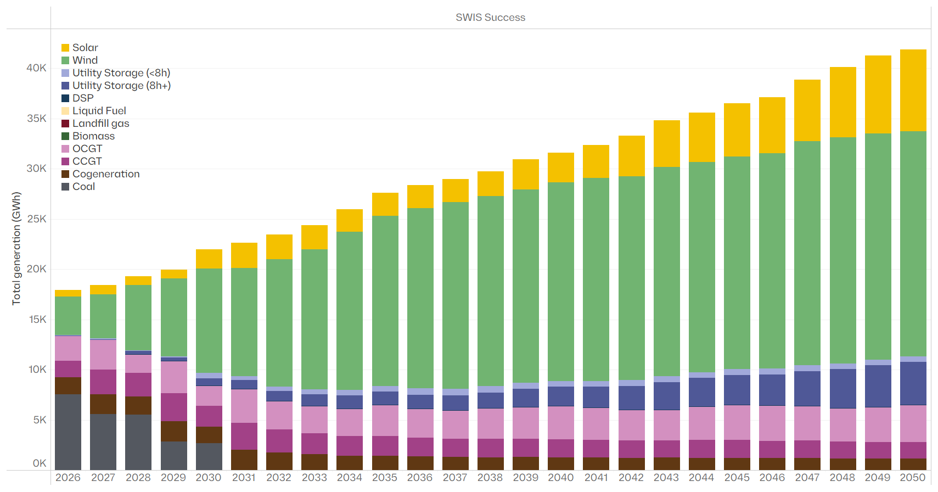
Our SWIS Success scenario describes a hopeful transition, supported by timely transmission and wind build-out. Figure 2 shows how generation changes over time. The system starts mostly with thermal plants, with coal supplying 42% of generation in CY 2026. By CY 2031, coal is retired and wind supplies most of the energy, with gas and storage firming. Solar generation slowly grows over time, peaking at 20% of generation in 2050.

Figure 2: Annual generation (GWh) by technology, SWIS Success, CY 2026 to CY 2050

Source: Endgame WEM price projection, Q3 2026.

Gas does a lot of work in this picture. In CY 2031, the first year without coal, gas-powered generation supplies around 36% of the system’s energy. Its share falls to about 20% by CY 2040, but it remains the firming resource.

Squeezing the gas

To test the daily fuel offtake constraint, we ran a Gas squeeze sensitivity on SWIS Success. Everything stays the same except for two changes. Gas available to generators is capped at 406 TJ/day, and plants can switch to liquid fuel if they have the functionality.

Over a year, 406 TJ/day is a lot of gas. The SWIS burns well under half of that for power in a typical year. So the constraint does not bite on annual volume. It bites on certain days, when demand is higher and renewable resources are lower.

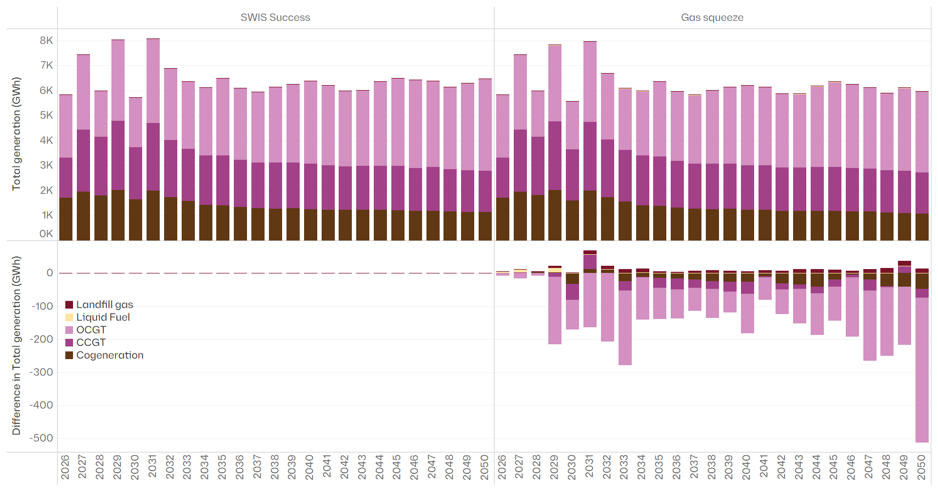
The bottom panel in Figure 3 shows how gas generation changes with the added constraint. Values below the line mean less gas generation in Gas Squeeze than in SWIS Success. From CY 2029, gas generation is lower in every year: by roughly 80 to 280 GWh a year through the 2030s and 2040s, and by more than 500 GWh in CY 2050. Most of that energy is replaced by solar and storage shifting across the day. Liquid fuel runs in CY 2026, 2027, 2029 and 2034, but never more than 13 GWh in a year.

Figure 3: Thermal generation (GWh) by technology, SWIS Success and Gas squeeze, and difference from SWIS Success

Source: Endgame WEM price projection, Q3 2026.

Small volumes, real price impact

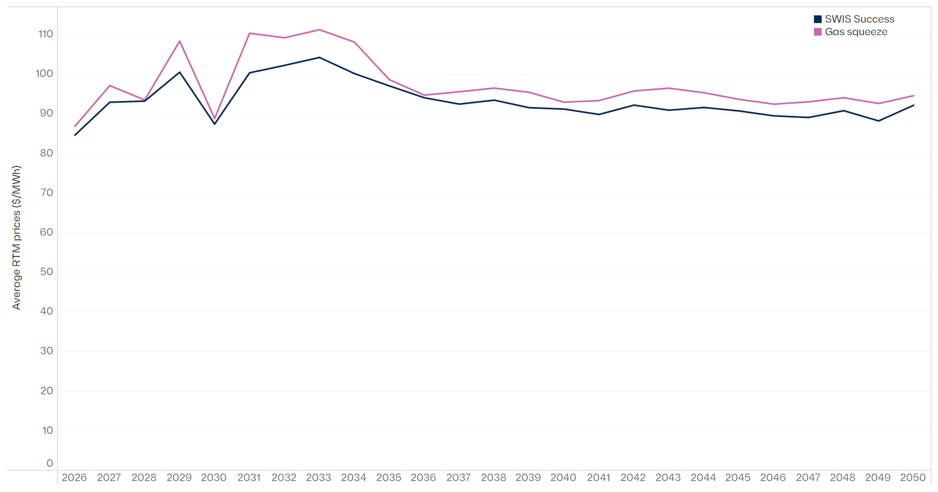
The squeeze raises average prices across the whole horizon (Figure 4). On constrained days, gas becomes scarce and more expensive resources then set the price more often; liquid fuel is called on in the tightest periods.

Figure 4: Average RTM price ($/MWh), SWIS Success and Gas squeeze, CY 2026 to CY 2050

Source: Endgame WEM price projection, Q3 2026. Time-weighted average RTM prices.

Two periods stand out:

  • CY 2029 to CY 2034. The squeeze adds $7 to $10/MWh (7% to 10%) in every year except CY 2030. This is the period when coal is retiring, and gas carries the most firming. Note that in 2030, CIS projects enter as renewable generation increases and prices drop.
  • CY 2037 onwards. Once new transmission projects enter, the renewable and storage fleet has matured, the increase settles at a persistent $2 to $6/MWh, averaging about $3.40/MWh.

The system copes, but it pays more to do so.

Resilience has a price

When gas is constrained, the system can’t firm renewables as well, and the SWIS has to rely on more expensive generation. Our Gas squeeze sensitivity tests one constraint, based on a real event. It does not yet test a worse renewable drought, a major outage or a more extreme weather event on top of that constraint.

As the SWIS becomes a weather-dependent system, knowing how it performs in bad conditions matters as much as knowing the central case. System planning exercises need more analysis similar to this, especially as the transition occurs.

Want to know more?

Our WEM price projection covers a range of scenarios and sensitivities. Subscribers receive the full report, a briefing, the assumptions and summary workbooks and half-hourly modelling results.

Join us at our upcoming WEM price projection seminar or get in touch.

Results are from Endgame’s Q3 2026 WEM price projection (PLEXOS dispatch model). Prices are real, time-weighted average RTM prices in 2026 dollars. CY means Capacity Year: CY 2026 runs from 1 October 2026 to 30 September 2027.


[1] AEMO, 2026 WEM ESOO, https://www.aemo.com.au/-/media/files/electricity/wem/planning_and_forecasting/esoo/2026/2026-wem-electricity-statement-of-opportunities.pdf?rev=80281c368251452c84bfa16ab4eb9fcd&sc_lang=en

Bell Bay Blues

Highlights from the Australian market

News from Japan

  • Paywalled: Kyushu Electric’s incoming president, Norihiro Nakamura, says the utility is considering building new nuclear capacity, as demand in the region grows from AI data centres and semiconductor hubs such as TSMC’s.
  • Paywalled: TEPCO is tightening its grid connection rules to stop data centre developers holding queue spots without firm plans; from October 2026, it will cancel requests if the initial construction deposit (10% of estimated costs) isn’t paid within three months, or if development plans change during the application stage.

Podcast of the week

Zugzwang: Episode 4 – Benchmarking battery optimisers

The latest episode of Zugzwang: The market modelling podcast is now available!

Jack Simpson and Oliver Nunn are joined by Rakhesh Martyn, founder and CEO of Hachiko, to unpack how battery optimisers actually capture value. 

Spotify: https://open.spotify.com/show/0346ILtbXgKJJIlOy64p1i
Apple Podcasts: https://podcasts.apple.com/us/podcast/zugzwang/id6801348317
YouTube: https://www.youtube.com/playlist?list=PLQ3gvq2Ccils
Electrifying the Light Vehicle Fleet

Movement-driven charging demand and the limits of residential-anchored network planning – a Byron Bay case study


Endgame Analytics is pleased to share the third instalment of our decarbonising transport research series, this time turning to the light vehicle fleet and what happens when a large, mobile block of EV charging demand hits a network sized for locals, not visitors.


We modelled a Byron Bay case study, using Compass IoT connected vehicle data to size what an additional 6,000 visiting EVs would do to peak demand for the local substation. This reflects a peak visitor day, when around 40,000 visitors join 11,500 residents, and assumes half of visiting vehicles are electric. We also test how charger speed and tariff-driven charging behaviour change the result.


Some key highlights:

  • The peak roughly doubles on convenience charging alone: Against an 11.8 MW summer baseline, 6,000 EVs charging on arrival lift the peak to 23.9–25.1 MW, a 2.0–2.1x multiplier, regardless of charger speed.
  • Price signals could make it worse, not better: Time-of-use and solar-sharer tariffs synchronise the fleet to commence charging at the same time. On Level 2 (15 kW) chargers, peak demand rises to 91.9 -98.4 MW, 7.8–8.4x the 11.8 MW baseline, against about 25 MW for convenience charging.
  • Even perfect coordination doesn’t fully solve it: even the theoretical best case lifts the peak to 1.07x the baseline (12.6 MW) at 50% EV penetration, which would be 1.7x the baseline (19.5 MW) if EV penetration reaches 100%.


Pricing alone won’t coordinate this load. Direct load control, dynamic operating envelopes, and recognising the value drivers place on mobility will all need to be part of the answer, alongside the case for network augmentation itself.

Read the full paper here

Fill out the form to download the PDF

Get in Touch

Endgame Analytics are helping clients navigate these interactions between policy, technology, and economic strategy.

  • Martin Chow, Director (Endgame Analytics) | E: martin.chow@endgameanalytics.com.au
  • Benedict Chin, Analyst (Endgame Analytics) | E: benedict.chin@endgameanalytics.com.au

Divide by zero

Highlights from the Australian market

  • The Coalition has pledged to repeal a swathe of climate policies within 30 days of taking office – scrapping the net zero target, safeguard mechanism, vehicle emissions standards, nuclear prohibitions and four offshore wind zones – with Angus Taylor saying “Australia has done its bit” to drive down emissions.
  • Victoria will ban datacentres from residential zones and within 150 m of homes, schools and childcare centres, and require them to supply their own renewable energy and storage; critics point out that the rules aren’t retrospective, exempting all approved projects and the eight applications already before the planning minister.
  • With AEMO forecasting that datacentre electricity use could triple by 2030, the AEMC has opened consultation on two rule changes from Minister Bowen that would make datacentres and other large loads pay their share of the network upgrades they trigger, and stop the cost of stranded assets being passed to other consumers if projects fall through. Submissions close 5 November.
  • Treasury’s Intergenerational Report 2026 names the energy transition as one of five forces reshaping the economy over the next 40 years, projecting that household energy costs will fall around 40% between 2030 and 2050 as homes electrify, and that data centres will make up almost 10% of NEM demand by 2050.
  • Woodside and Burrup Peninsula Traditional Owners are locked in a $300 million compensation dispute over the 1998 land access agreement for the North West Shelf’s Karratha Gas Plant – the Ngarluma Yindjibarndi Foundation is seeking $390 million over 12 years against Woodside’s offer of $87 million.
  • Chris Bowen is travelling to India and Saudi Arabia to bolster fuel security, with plans to visit the world’s largest refinery at Jamnagar and meet Saudi Energy Minister Prince Abdulaziz bin Salman about the closure of the East-West pipeline, ahead of COP31.
  • Sunshine and wind met a record 80.4% of demand on the NEM on Saturday 19th September, with rooftop solar alone supplying more than half the grid’s power for 30 minutes around lunchtime.

News from Japan

Podcast of the week

Columbia Energy Exchange looks at the Iran war six months on. With crude near $107 a barrel, Hormuz tanker traffic reduced and Saudi Arabia’s East-West Pipeline offline, they warn that the market buffers that cushioned the early shock are running out.

Data, Dalby, Data

Highlights from the Australian market

  • Anthropic has signed a lease for Australia’s largest data centre, the $32 billion Western Downs Digital Park near Dalby in Queensland, which will power Claude AI inference and, once built, draw electricity equivalent to 1.5 million households.
  • Australia’s dependence on gas generation during the evening peak has fallen by almost 70% in the year to August 2026, with batteries now covering 49% of evening dispatchable power, up from just 0.4% in 2020.
  • In the same vein, new ANU modelling finds Australia doesn’t need more gas-fired generation to meet future energy needs, showing pumped hydro and batteries can balance a fully renewable grid at a comparable cost.
  • NSW’s renewable transmission delivery agency EnergyCo has underspent its budget by $939 million over the past two years, a symptom of approval delays that now leave the state roughly 7.9GW short of its 2030 renewable energy target.
  • ARENA has committed $8.2 million to a home electrification trial that aims to make the transition from gas to electricity easier, letting up to 1,000 Canberra households bundle solar, batteries and EVs onto one digital platform.
  • IEEFA and Green Energy Markets’ Australian Renewable Energy Scorecard finds Australia has enough wind and solar in the pipeline – 34GW of solar and 17GW of wind fully approved – to hit the 82% 2030 renewables target, but actual construction is falling far short.  

News from Japan

  • Chubu Electric Power has withdrawn its restart applications for Hamaoka Units 3 and 4 after an independent committee found staff had for years manipulated seismic safety data submitted to Japan’s nuclear regulator, leaving it unclear if or when the reactors will ever restart.

Podcast of the week

Zugzwang: Episode 3 – What is transmission really worth?

The latest episode of Zugzwang: The market modelling podcast is now available!

Jack Simpson, Oliver Nunn and Jabez Wilson discuss modelling philosophy and put it to work on one of the NEM’s most contested assets: transmission. Listen now on your favourite platform.

Spotify: https://open.spotify.com/show/0346ILtbXgKJJIlOy64p1i

Apple Podcasts: https://podcasts.apple.com/us/podcast/zugzwang/id6801348317

YouTube: https://www.youtube.com/playlist?list=PLQ3gvq2Ccils

Contact

a. A
Level 31, 9 Castlereagh St, Sydney NSW 2000
a.
Level 31, 9 Castlereagh St, Sydney NSW 2000

Oops! We could not locate your form.

Get in touch.